How to Perform a Lease Classification Test

What is a lease classification test?
A lease classification test determines whether a lessee should account for an agreement as an operating lease or finance lease under ASC 842. It evaluates ownership transfer, purchase options, economic life, present value, and whether the underlying asset is specialized.
A lease classification test determines whether a lease should be classified as an operating lease or a finance lease under ASC 842. The test evaluates five criteria related to ownership, purchase options, the asset's economic life, the present value of lease payments, and the specialized nature of the underlying asset.
For commercial tenants and accounting teams, proper classification matters because operating and finance leases follow different expense recognition requirements. Although both generally appear on the balance sheet, their effects on financial reporting are not identical.
The test involves three steps: gathering the relevant lease information, evaluating the five ASC 842 criteria, and documenting the classification decision at lease commencement.
This guide explains each criterion, provides a decision flowchart, and demonstrates how to classify a lease using a worked example.
Free Lease Classification Test: Occupier's Lease Classification Test Excel Template helps accounting teams evaluate lease terms, document classification decisions, and prepare supporting records for review.
What Is a Lease Classification Test?
A lease classification test is an accounting assessment used to determine whether a lease qualifies as an operating lease or finance lease under ASC 842.
Under the previous ASC 840 guidance, leases were generally classified as capital or operating leases. ASC 842 replaced the term "capital lease with finance lease and introduced balance sheet recognition for most operating leases.
A finance lease generally represents an arrangement where the lessee obtains substantially all the economic benefits associated with the underlying asset.
An operating lease generally provides the right to use an asset for a specified period without meeting the finance lease classification criteria.
Classification is assessed at lease commencement, when the underlying asset becomes available for the lessee's use, rather than simply when the agreement is signed.
The resulting classification determines how lease costs are recognized and presented in financial statements.
What Are the Five Lease Classification Criteria Under ASC 842?
ASC 842-10-25-2 establishes five criteria for lessees.
If a lease meets any one of these criteria at commencement, it is classified as a finance lease. If none apply, the arrangement is classified as an operating lease.
1. Transfer of Ownership
The first criterion considers whether ownership of the underlying asset transfers to the lessee by the end of the lease term.
If the agreement provides for ownership to transfer automatically, the lease meets the finance lease classification requirement.
For example, a company might lease specialized manufacturing equipment under an agreement that transfers legal title to the company after the final scheduled payment.
An optional purchase requiring a separate decision should instead be considered under the purchase option criterion.
2. Purchase Option Reasonably Certain to Be Exercised
The second criterion evaluates whether the lessee has an option to purchase the asset and is reasonably certain to exercise it.
Reasonably certain represents a high threshold and requires consideration of the economic incentives surrounding the decision.
Relevant factors may include the purchase price compared with expected market value, the importance of the equipment to operations, and the cost of replacing it.
For example, a manufacturing company might have the option to purchase leased equipment for $5,000 when its expected market value is $80,000.
That substantial economic incentive could support a conclusion that the option is reasonably certain to be exercised.
3. Lease Term Covers a Major Part of Economic Life
The third criterion examines whether the lease term covers a major part of the asset's remaining economic life.
For example, equipment with an estimated remaining economic life of eight years might be leased for seven years.
The calculation would be:
7 ÷ 8 × 100 = 87.5%
That suggests the lease covers a substantial portion of the asset's remaining economic life.
ASC 842 does not prescribe a mandatory 75% threshold. However, organizations may reasonably use 75% as an accounting-policy guideline when applying the classification criteria consistently.
This criterion is not applied when lease commencement occurs at or near the end of the asset's economic life.
4. Present Value Represents Substantially All Fair Value
The fourth criterion considers whether the present value of lease payments, together with any applicable residual value guarantee not already included in those payments, represents substantially all the underlying asset's fair value.
The present value calculation accounts for the timing of payments and the appropriate discount rate.
For example, suppose the present value of qualifying payments is $270,000 and the underlying asset's fair value is $300,000.
The ratio would equal:
$270,000 ÷ $300,000 × 100 = 90%
This would commonly support finance lease classification.
Although 90% is often used as a reasonable benchmark, ASC 842 does not establish it as a mandatory bright-line threshold.
Accounting teams should apply their documented policies consistently and consider the complete facts.
The <a href="https://dart.deloitte.com/USDART/home/codification/broad-transactions/asc842-10/roadmap-leasing/chapter-8-lessee-accounting/8-3-lease-classification" rel="nofollow">Deloitte ASC 842 lease classification guidance</a> provides additional interpretation of these criteria.
5. Specialized Asset With No Alternative Use
The fifth criterion considers whether the underlying asset is so specialized that it is expected to have no alternative use to the lessor after the lease term.
For example, a company might lease custom manufacturing equipment designed exclusively for its production process.
If the equipment cannot reasonably be repurposed for another customer after the agreement expires, the arrangement may meet this criterion.
The assessment focuses on the asset's expected alternative use to the lessor, not merely whether the lessee considers it important.
Lease Classification Test Flowchart
The following decision flow shows how accounting teams can evaluate the five ASC 842 criteria.
START: Review the lease at commencement
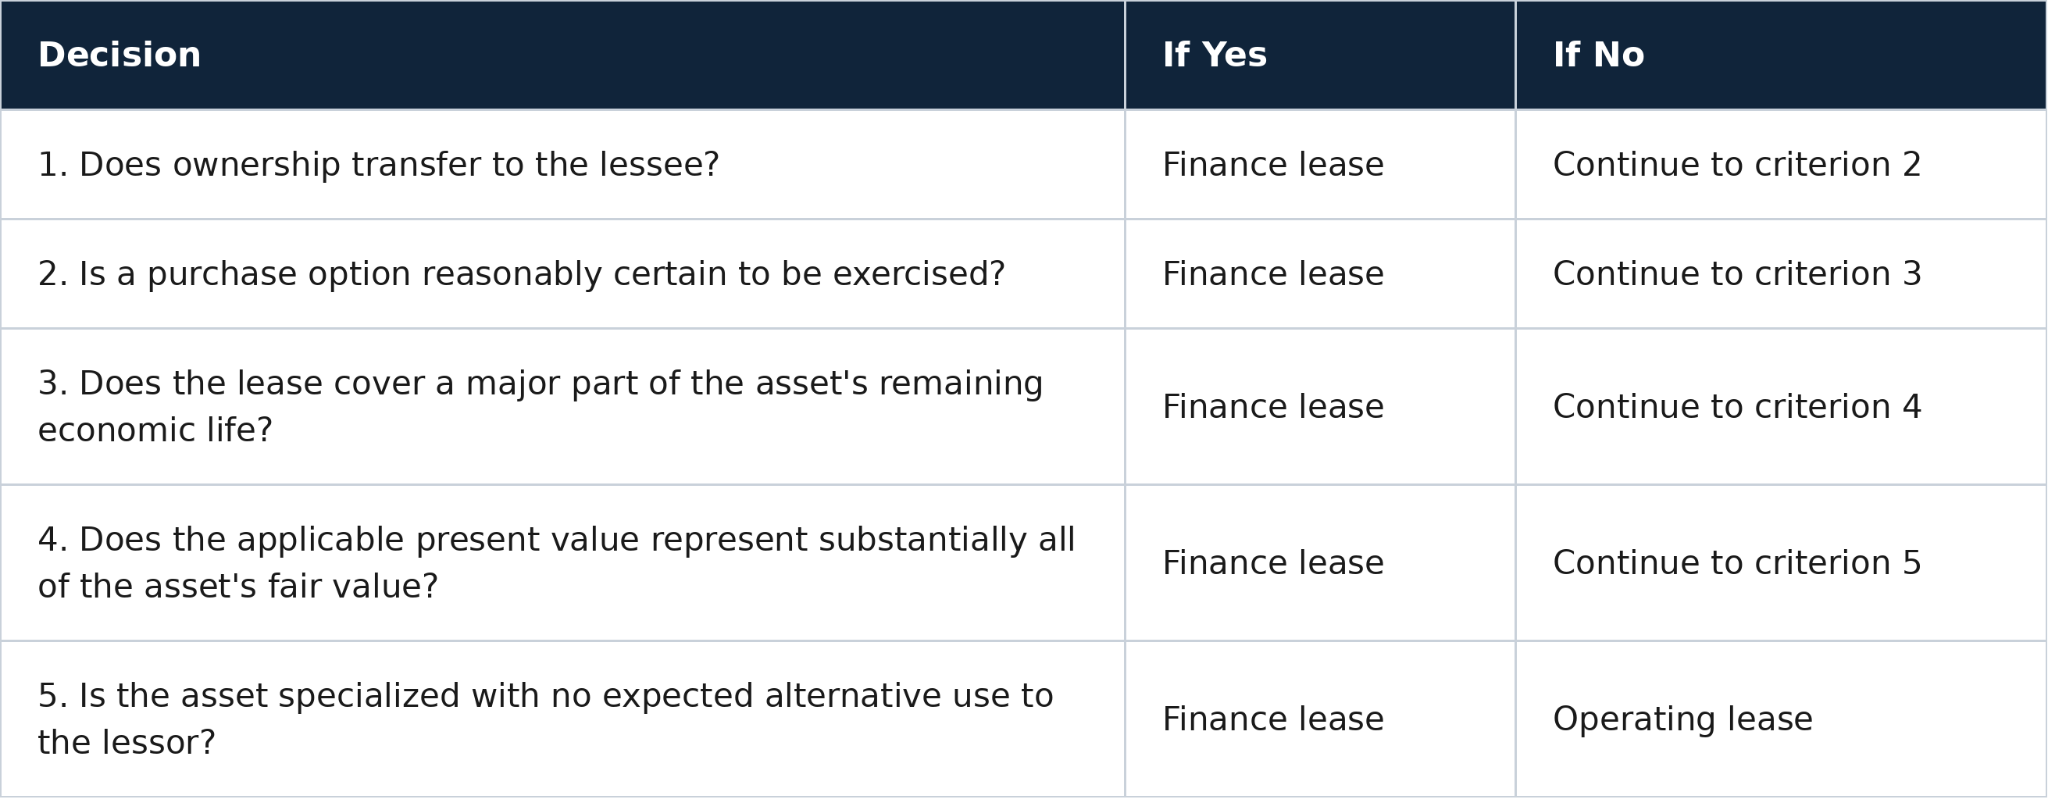
Decision path: Start → Ownership → Purchase option → Economic life → Present value → Specialized asset → Operating lease if every answer is No.
Any Yes answer leads to finance lease classification.
Accounting teams should document the supporting calculations and assumptions, particularly when evaluating economic life, fair value, and purchase options.
A lease that appears straightforward can still require professional judgment when contractual provisions or economic incentives are unusual.
Lease Classification Test: Worked Example
Consider a commercial tenant leasing office equipment for five years.
The company wants to determine whether the agreement qualifies as an operating or finance lease under ASC 842.
Example Lease Details
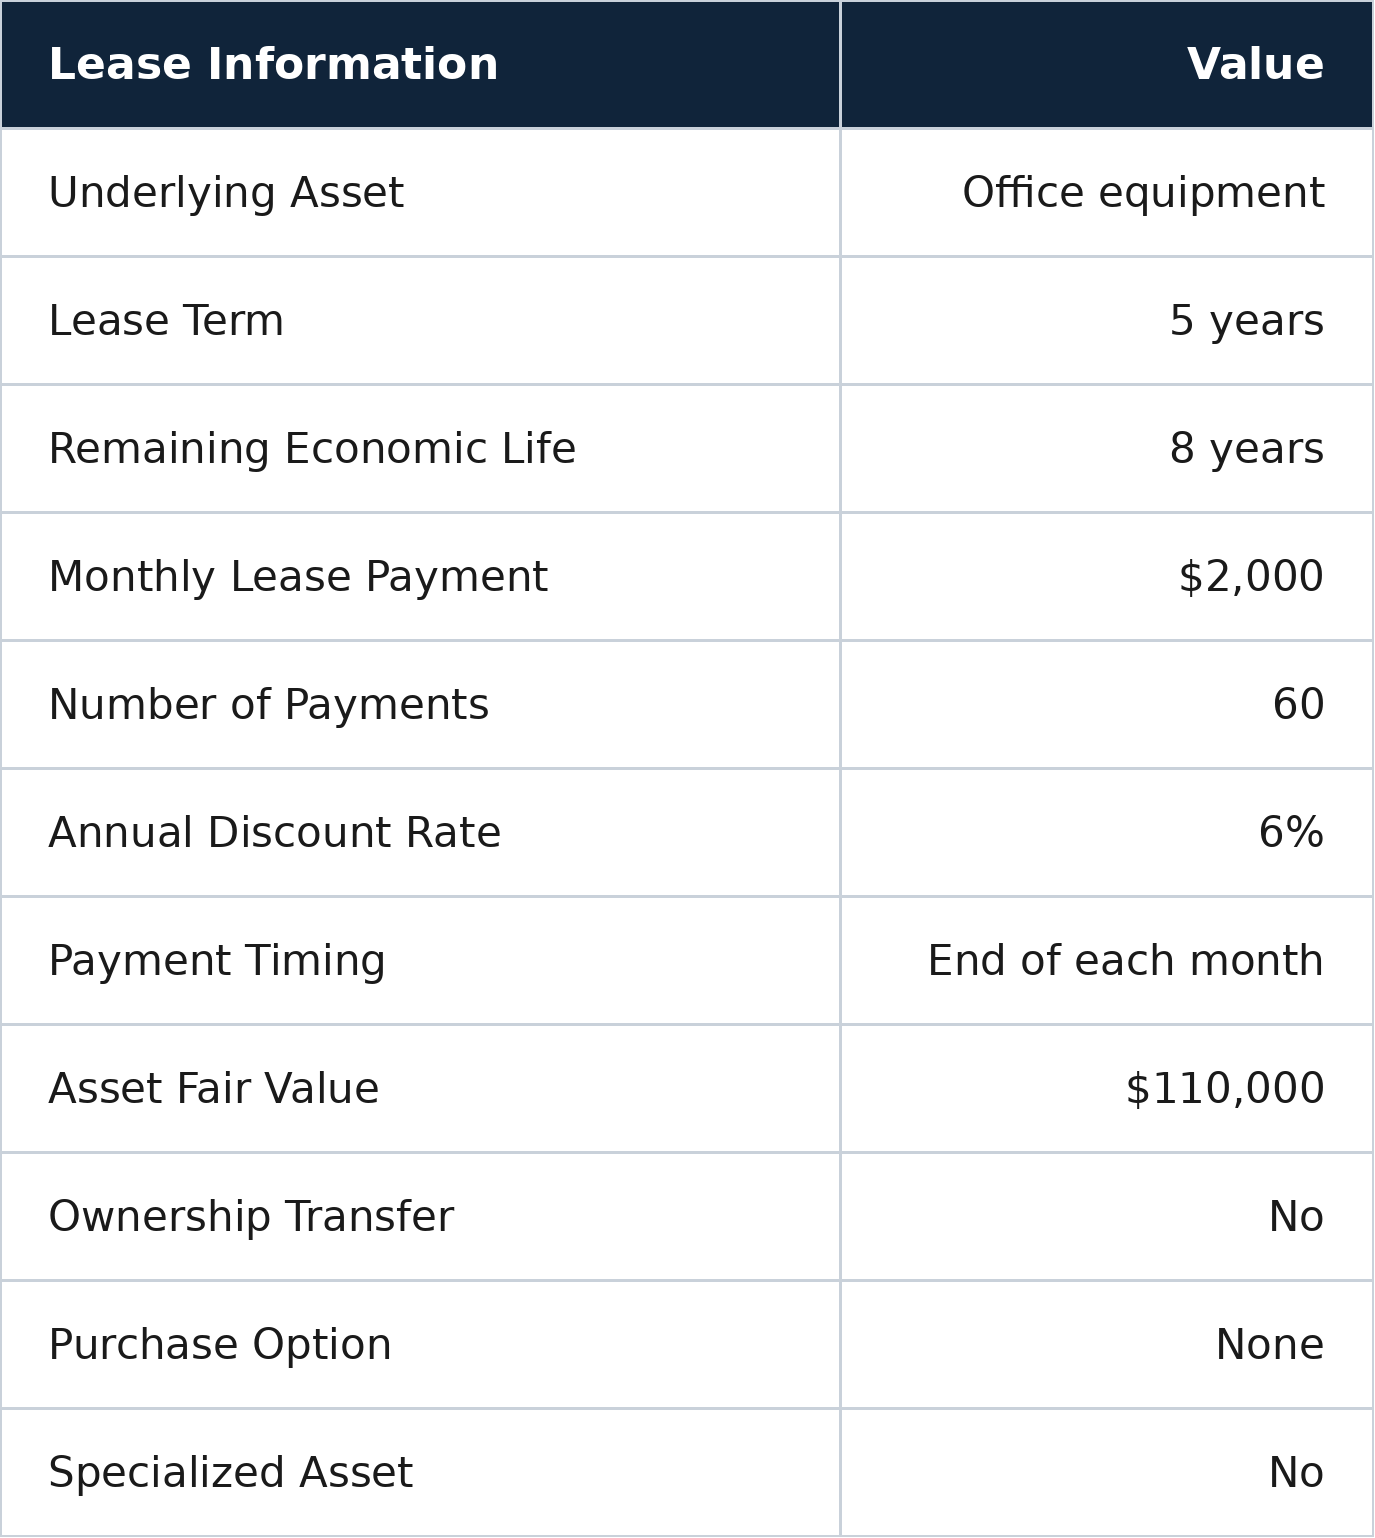
Assume there are no additional payments or residual value guarantees affecting the classification calculation.
Step 1: Evaluate Ownership and Purchase Options
The agreement does not transfer ownership to the tenant.
It also contains no purchase option.
Therefore, neither of the first two finance lease criteria is met.
Step 2: Compare Lease Term and Economic Life
The lease lasts five years, while the equipment has eight years of remaining economic life.
5 ÷ 8 × 100 = 62.5%
Using a consistently applied 75% guideline, the lease does not cover a major part of the asset's remaining economic life.
Step 3: Calculate Present Value of Payments
The tenant pays $2,000 monthly for 60 months.
Using a 6% annual discount rate, equivalent to 0.5% monthly for this illustrative calculation, the present value of payments is approximately $103,451.
The present value as a percentage of fair value is:
$103,451 ÷ $110,000 × 100 = 94.05%
Because this exceeds a commonly applied 90% benchmark, the lease meets the substantially-all criterion under that accounting policy.
Step 4: Determine the Classification
The agreement does not transfer ownership, contain a purchase option, or involve specialized equipment.
Its term also falls below the illustrative economic-life threshold.
However, the present value criterion is met.
Result: Finance lease under ASC 842.
Only one criterion needs to be satisfied.
This example demonstrates why accountants should evaluate all five conditions rather than making a classification decision based only on the lease term.
How Does Lease Classification Affect Accounting?
Operating and finance leases generally require lessees to recognize a right-of-use (ROU) asset and lease liability at commencement.
The key difference is how expenses are recognized afterward.
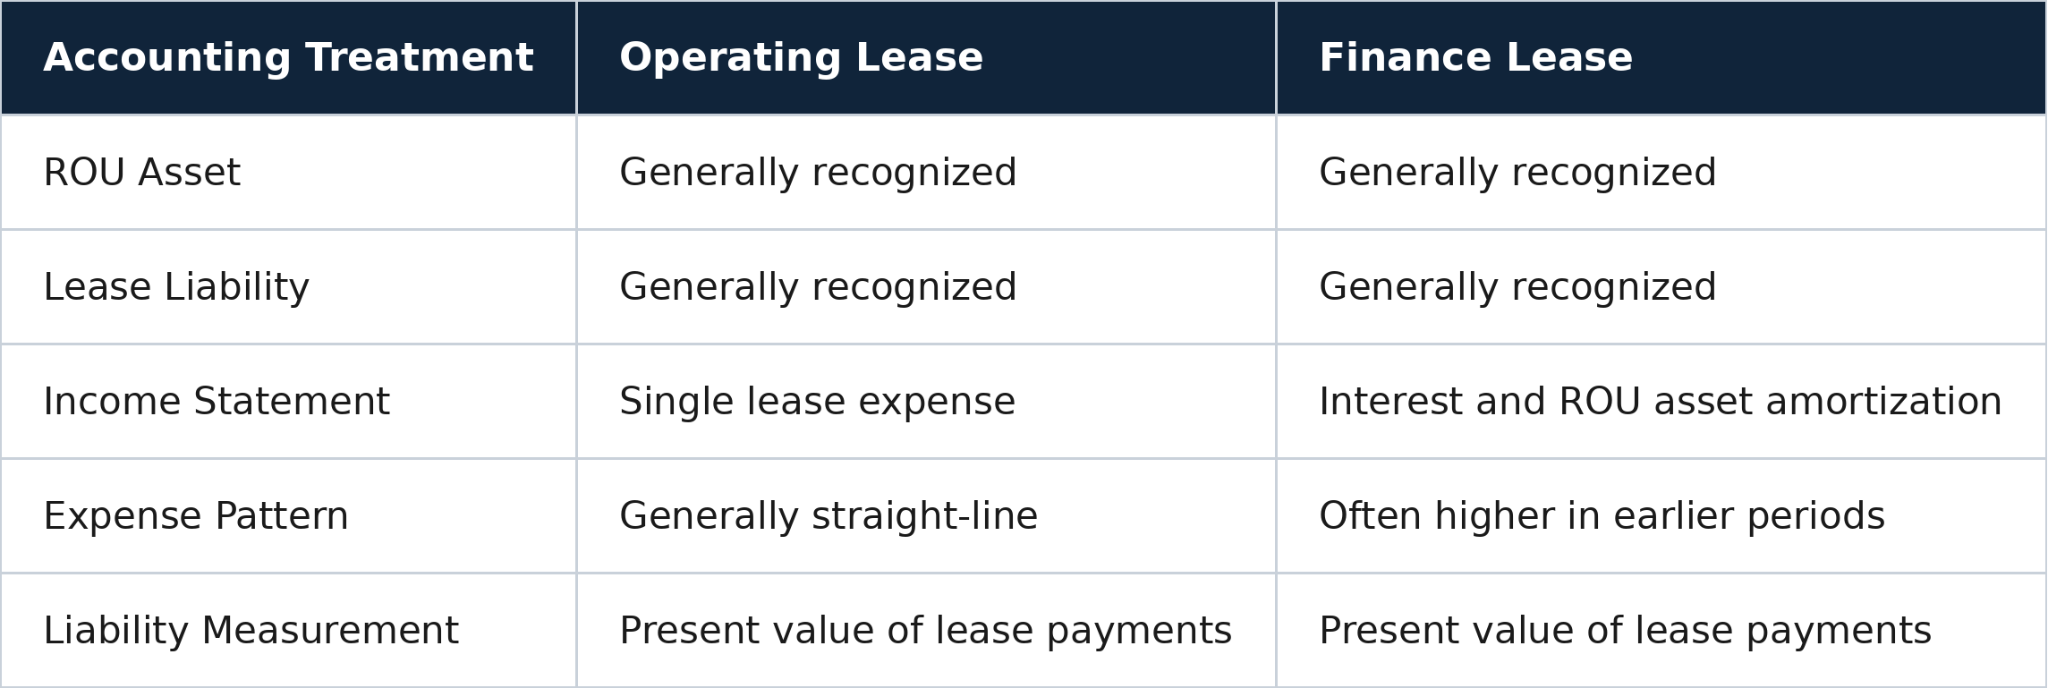
For operating leases, accounting teams generally recognize a single lease expense on a straight-line basis.
For finance leases, interest on the outstanding liability and amortization of the ROU asset are recognized separately.
A detailed finance lease accounting schedule helps illustrate how those balances and expenses change throughout the lease term.
Classification also affects presentation and disclosure requirements, making consistent documentation important during financial reviews.
ASC 842 vs. IFRS 16 Lease Classification
ASC 842 and IFRS 16 both require recognition of most leases on a lessee's balance sheet, but their expense recognition approaches differ.
Under ASC 842, lessees classify leases as either operating or finance leases.
IFRS 16 generally applies a single lessee accounting model rather than requiring the same operating-versus-finance classification.
Under IFRS 16, lessees typically recognize depreciation of the right-of-use asset and interest on the lease liability.
Both standards provide certain recognition exemptions for qualifying short-term leases. IFRS 16 also includes an exemption for leases of low-value underlying assets.
The IFRS Foundation's IFRS 16 guidance describes the international lease accounting requirements.
Organizations reporting under multiple accounting frameworks should ensure their procedures reflect the applicable standard.
When Should a Lease Classification Be Reassessed?
Lease classification is generally established at commencement and does not need to be reassessed every reporting period.
However, certain changes can require a new assessment.
These include lease modifications that are not accounted for as separate contracts, changes in the lease term, or changes in whether a purchase option is reasonably certain to be exercised.
For example, a tenant might extend a lease significantly beyond its original term.
The extension could affect whether the arrangement covers a major part of the asset's remaining economic life.
Accounting teams should review the revised terms and determine whether reclassification is required under ASC 842.
Not every rent adjustment triggers reclassification. The reason for the change and the applicable accounting guidance matter.
Common Lease Classification Mistakes
Incorrect classification often results from incomplete information or inconsistent accounting assumptions.
One common problem is treating the 75% and 90% guidelines as mandatory rules rather than reasonable interpretations of ASC 842 terminology.
Another is calculating the present value using an incorrect discount rate or overlooking payments and residual guarantees relevant to classification.
Accounting teams may also overlook purchase options, use an incorrect lease term, or fail to review amendments that change the classification assessment.
Maintaining documented policies and consistent procedures helps reduce these errors.
Occupier's overview of ASC 842 lease accounting provides additional context on how lease classification fits into recognition, measurement, and reporting.
How Can Software Support Lease Classification?
Businesses with multiple leases may need to assess different payment structures, purchase options, and economic-life assumptions across their portfolios.
Manual spreadsheets can handle straightforward calculations, but maintaining consistent records becomes difficult when agreements are amended.
Using lease accounting software allows finance teams to organize lease information, calculate accounting schedules, and maintain supporting records.
Occupier connects lease data with accounting workflows, helping teams manage operating and finance lease calculations while reducing repetitive manual work.
A well-documented classification assessment provides the foundation for accurate lease accounting, particularly when agreements change or reporting teams need to review previous decisions.
Lease Classification Test FAQs
1. What is a lease classification test?
A lease classification test determines whether a lessee should account for an agreement as an operating lease or finance lease under ASC 842. It evaluates ownership transfer, purchase options, economic life, present value, and whether the underlying asset is specialized.
2. What are the five criteria for finance lease classification?
The five criteria are ownership transfer, a purchase option reasonably certain to be exercised, a lease term covering a major part of the asset's remaining economic life, present value representing substantially all fair value, and an asset with no alternative use to the lessor.
3. Are the 75% and 90% lease classification tests mandatory?
No. ASC 842 does not prescribe mandatory 75% or 90% bright-line thresholds. They are commonly used as reasonable approaches to interpreting the economic-life and fair-value criteria. Organizations should apply their documented accounting policies consistently.
4. What happens if none of the five criteria are met?
If none of the five finance lease criteria are met, the lessee generally classifies the agreement as an operating lease under ASC 842. The lease normally still requires recognition of an ROU asset and lease liability, unless an applicable recognition exemption is elected.
5. When should lease classification be performed?
Lease classification is assessed at commencement, when the underlying asset becomes available for use. Reassessment may be necessary following certain changes in lease terms, purchase-option assessments, or modifications that are not accounted for as separate contracts.
6. Where can I download a lease classification test template?
Occupier provides a free Lease Classification Test Excel Template for evaluating operating and finance lease criteria. The resource helps accounting teams record lease information, assess classification requirements, and maintain supporting documentation.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required